Accredited Investors Explained: How Sophisticated Investors Access Private Markets, Alternative Investments & Institutional Strategies
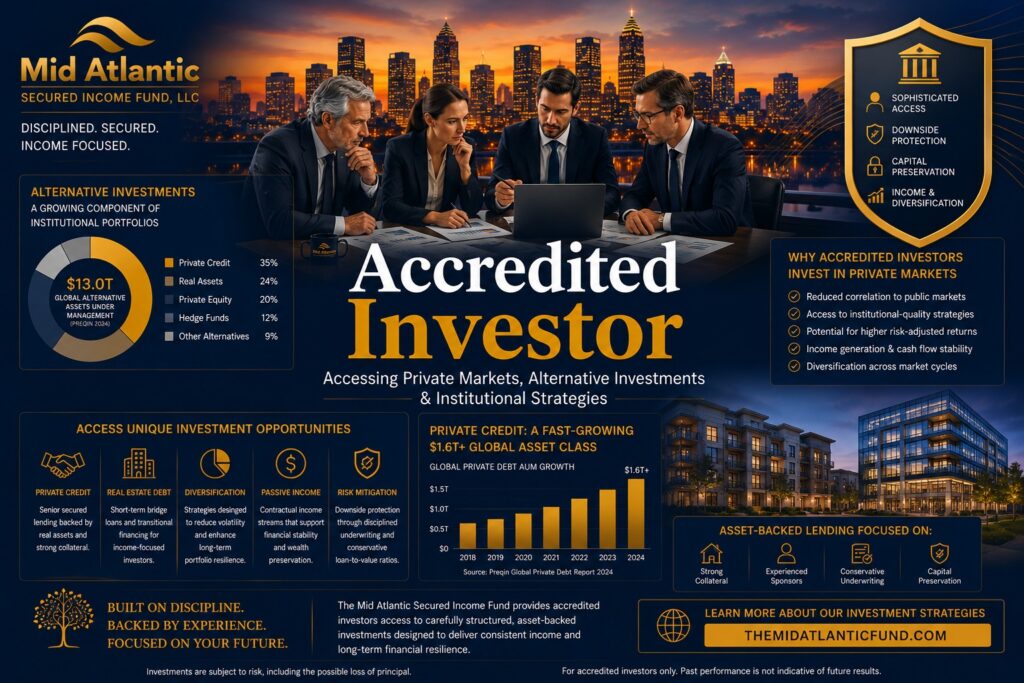
For decades, many of the most attractive investment opportunities in the world were largely inaccessible to the average investor. Private credit funds. Institutional real estate debt strategies. Alternative income investments. Specialty finance. Private equity. Structured lending. These opportunities historically existed behind the walls of pension funds, insurance companies, endowments, family offices, and ultra-high-net-worth investors. Today, accredited investors increasingly have access to portions of these private markets. As public markets become more volatile and traditional stock-and-bond portfolios face new challenges from inflation, interest-rate shifts, and economic uncertainty, sophisticated investors are looking beyond conventional investment frameworks. The rise of private markets and alternative investments is not simply a trend. It represents a structural transformation in how wealth is being built, preserved, diversified, and protected. What Is an Accredited Investor? Direct Answer An accredited investor is an individual or entity that meets specific financial criteria established by the U.S. Securities and Exchange Commission (SEC), allowing access to certain private investment opportunities not registered with the SEC. Accredited investor status is intended to identify investors who may possess the financial sophistication, resources, or ability to withstand higher investment risks associated with private offerings. Accredited Investor Requirements Under current SEC guidelines, an individual may qualify as an accredited investor if they meet one or more of the following criteria: Income-Based Qualification An individual generally qualifies if they have: earned income exceeding $200,000 individually in each of the last two years, or joint income exceeding $300,000 with a spouse or spousal equivalent, with a reasonable expectation of maintaining that income level. Net Worth Qualification An investor may also qualify if they possess: a net worth exceeding $1 million, either individually or jointly with a spouse, excluding the value of a primary residence. Professional Certifications Certain financial professionals may qualify through recognized credentials, including: Series 7, Series 65, and Series 82 licenses. Entity-Based Qualification Certain entities may qualify based on: asset size, ownership structure, or institutional status. Why Accredited Investor Status Matters Accredited investor status provides access to segments of the market unavailable through most traditional brokerage accounts. This may include: private credit funds, real estate debt investments, private equity, venture capital, hedge funds, specialty finance, structured lending, and institutional alternative investments. For sophisticated investors, these opportunities may offer: diversification, contractual income, inflation resilience, and lower correlation to public markets. The Evolution of Private Markets Private markets have grown dramatically over the past two decades. According to Preqin and BlackRock research, global alternative investment assets have expanded into the trillions of dollars, driven largely by institutional demand. Several factors are contributing to this growth: Public Market Volatility Investors increasingly seek strategies less dependent on daily stock market fluctuations. Yield Compression Traditional fixed-income investments have struggled to provide attractive real yields during inflationary periods. Institutional Portfolio Shifts Large pension funds and endowments have steadily increased allocations to alternatives, including private credit and real assets. Inflation Concerns Income-generating alternative assets may offer stronger inflation sensitivity compared to traditional bonds. Why Sophisticated Investors Are Moving Beyond Traditional Portfolios For decades, the classic 60/40 portfolio model dominated wealth management. But modern markets have introduced new challenges: persistent inflation, elevated interest rates, increased volatility, geopolitical instability, and changing correlations between stocks and bonds. Sophisticated investors increasingly recognize the importance of: diversification beyond public equities, alternative income streams, downside protection, and real asset exposure. What Are Alternative Investments? Direct Answer Alternative investments are non-traditional assets that exist outside publicly traded stocks, bonds, and cash equivalents. Examples include: private credit, real estate debt, private equity, infrastructure, hedge funds, specialty finance, and asset-backed lending. Alternative investments may offer: diversification, contractual income, inflation resilience, and differentiated return drivers. Understanding Private Credit Private credit has emerged as one of the fastest-growing alternative asset classes globally. What Is Private Credit? Private credit refers to non-bank lending arrangements where investors provide capital directly to borrowers outside traditional public bond markets. Strategies may include: bridge lending, senior secured lending, construction financing, receivables financing, real estate-backed lending, and specialty commercial finance. Why Accredited Investors Use Private Credit 1. Income Generation Private credit investments often generate contractual interest income. This may appeal to: retirees, family offices, passive income investors, and wealth preservation strategies. 2. Senior Secured Structures Many private lending strategies operate in senior lien positions, potentially improving downside protection. 3. Asset-Backed Exposure Collateral-backed structures tied to real estate or other hard assets may reduce certain forms of investment risk. 4. Lower Public Market Correlation Private credit may exhibit lower correlation to stock market volatility than many traditional investments. Are Alternative Investments Risky? Direct Answer Alternative investments can involve significant risks, including illiquidity, underwriting risk, market risk, and operational complexity. However, when structured conservatively, certain alternative investments may improve diversification and risk-adjusted portfolio resilience. Risk levels vary widely depending on: investment structure, leverage, collateral quality, manager experience, and economic conditions. Understanding Risk in Private Markets Sophisticated investors focus heavily on understanding: downside risk, capital structure, underwriting quality, and liquidity terms. Private investments are not inherently safer or riskier than public investments. What matters is: structure, discipline, and alignment. The Institutional Investment Framework Institutional investors rarely rely on a single asset class. Instead, portfolios are often designed around: Objective Institutional Approach Income Generation Private credit, dividend strategies Inflation Mitigation Real assets, real estate Diversification Alternative allocations Downside Protection Senior secured positioning Long-Term Growth Multi-asset exposure Volatility Reduction Lower correlation strategies Why Wealthy Investors Prioritize Diversification Diversification remains one of the most powerful risk management tools available. True diversification extends beyond simply owning many stocks. Sophisticated investors diversify across: asset classes, income streams, geographies, durations, liquidity profiles, and economic sensitivities. Real Estate and Accredited Investors Real estate remains a cornerstone of many institutional portfolios. Accredited investors increasingly gain exposure through: real estate debt funds, bridge lending, construction financing, and asset-backed lending strategies. Many investors prefer debt exposure rather than direct property ownership because it may provide: contractual income, reduced operational burden, and senior secured positioning. Inflation, Interest Rates & Alternative Investments Inflation has fundamentally reshaped portfolio construction. According to the Bureau of Labor