Retirement capital has a different job than opportunistic capital. It may need to support planned distributions, preserve purchasing power over a long time horizon, and remain available when personal or family circumstances change. That is why evaluating high yield retirement investments requires more than comparing a stated yield. The more useful question is whether the investment’s return profile, collateral, liquidity, fees, and downside risks fit the role it would play in a retirement portfolio.
For accredited investors, private real estate credit can be one area to evaluate. It is not a substitute for cash reserves or publicly traded holdings, and it is not appropriate for every retirement account. But a carefully underwritten private credit strategy may offer a distinct source of current income when its structure, risks, and limitations are clearly understood.
What “High Yield” Should Mean in Retirement Planning
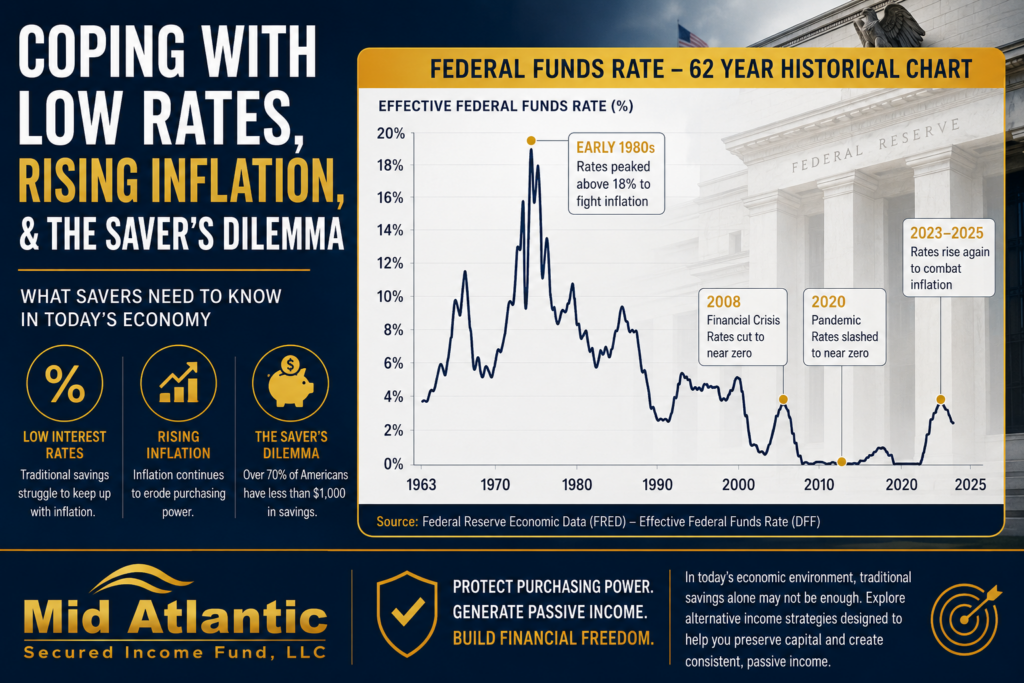
A higher stated yield is not, by itself, evidence of a better retirement investment. Yield can reflect many factors: borrower credit quality, the nature and value of pledged collateral, loan structure, duration, leverage, market conditions, fees, and the degree of illiquidity an investor accepts. It can also reflect risks that are not apparent from a headline number.
For retirement-focused investors, the objective is usually not to seek the highest available income at any cost. It is to pursue income while maintaining discipline around capital preservation. That requires asking what supports the expected return and what could impair it.
Private credit illustrates the distinction. A loan secured by a first-position lien on real estate may have a defined collateral position and contractual payment terms. Those features can be meaningful in a workout or recovery scenario, but they do not remove risk. Property values can decline, borrowers can default, projects can face delays, legal enforcement can take time, and the value realized from collateral may be less than anticipated.
A prudent retirement allocation should treat yield as one decision factor within a wider underwriting framework.
How to Evaluate High Yield Retirement Investments
The central due-diligence task is to identify the source of income and the protections, if any, that stand between an investment loss and the investor’s capital. This is particularly relevant in private-market offerings, where information may be less standardized than in public securities.
Start with the income source
An investor should be able to describe, in plain language, how the strategy is expected to generate income. In a private credit fund, income may generally arise from interest and other loan-related payments made by borrowers. The quality and consistency of that income depend on the underlying loans, borrower performance, portfolio construction, expenses, and the manager’s ability to originate and monitor credit responsibly.
Avoid treating distributions as proof that an investment is performing as expected over the long term. Distributions can be affected by many factors, including loan repayments, new originations, reserve decisions, expenses, and the terms of the offering. Review the offering documents to understand how distributions are determined and whether they may be changed, deferred, or suspended under applicable terms.
Examine collateral and lien priority
Collateral is often central to a real estate credit strategy. Senior-secured, first-position real estate lending places the lender ahead of junior lienholders with respect to the pledged property, subject to the loan documents and applicable law. This priority can be an important risk-control feature, especially when paired with conservative underwriting and active asset management.
Still, lien position should not be confused with certainty of repayment. Investors should understand the type of property securing a loan, the condition and marketability of that property, the borrower’s business plan, insurance requirements, title and legal considerations, and the potential costs and timing of enforcement. Collateral quality matters because recovery depends not only on having a claim, but also on the underlying asset’s value and the practical ability to realize it.
Treat liquidity as a core retirement risk
Illiquidity deserves the same attention as yield. Private fund interests may not be readily sold, may have limited or no redemption opportunities, and may require an investor to hold the position for an extended period. A retirement investor who may need funds for required expenses, healthcare, charitable commitments, or estate planning should maintain appropriate liquidity outside an illiquid allocation.
Read the offering documents carefully for transfer restrictions, redemption provisions, lockup conditions, valuation policies, and circumstances that could limit withdrawals. A stated liquidity feature is not the same as immediate access to capital. The governing documents control.
Review the manager’s underwriting process
A private credit strategy is ultimately a credit-selection and asset-management strategy. The stated investment mandate should explain what types of loans may be made, how they are sourced, what collateral may support them, and what concentration or underwriting parameters apply.
For a strategy focused on senior-secured real estate credit, disciplined underwriting may include an evaluation of the borrower, property, business plan, collateral documentation, market conditions, and exit assumptions. Investors should also ask how the manager monitors loans after closing, addresses covenant or payment issues, manages extensions or modifications, and handles impaired assets.
This process matters more than a promotional description of a lending category. A sound mandate can still produce losses if assumptions prove wrong or market conditions shift. Conversely, detailed reporting and a transparent discussion of portfolio risks can help investors make more informed decisions.
Fees, Valuation, and Reporting Deserve Equal Attention
Net return matters more than gross return. Investors should review all fees and expenses described in the offering materials, including management fees, organizational expenses, servicing expenses, incentive-based compensation where applicable, and any other costs that may reduce investment results.
Valuation is another essential question. Unlike a publicly traded security with a continuously quoted market price, private assets may be valued under manager-established policies and procedures. Ask how loans and collateral are valued, how often valuations are reviewed, when impairments may be recognized, and what independent oversight or third-party inputs are used where applicable.
Transparent reporting supports informed oversight. Useful reports generally help investors understand portfolio composition, loan performance, concentrations, maturity and repayment activity, material credit developments, expenses, and valuation methodology. Reporting cannot eliminate investment risk, but it can reduce the uncertainty that comes from investing without visibility into the portfolio.
Private Real Estate Credit in a Retirement Allocation
A private real estate credit allocation may be considered by accredited investors seeking exposure to contractual income backed by real estate collateral. Its suitability depends on the investor’s objectives, time horizon, liquidity needs, existing holdings, risk tolerance, and ability to bear loss.
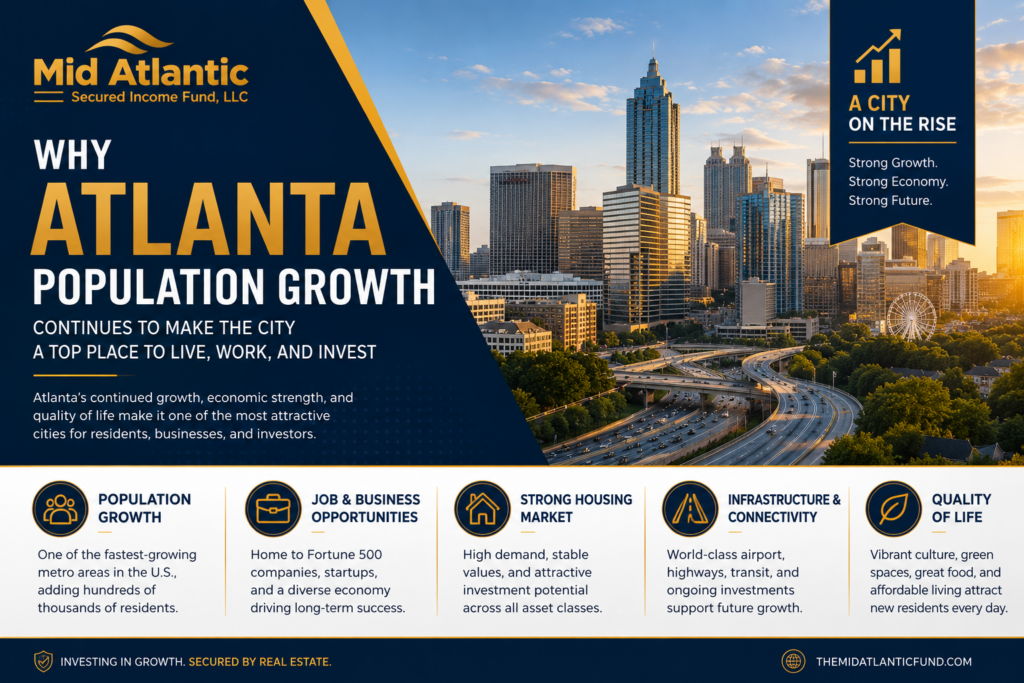
At Mid Atlantic Secured Income Fund, the investor offering is centered on a private credit fund that emphasizes senior-secured, first-position real estate lending, collateral quality, disciplined underwriting, capital-preservation objectives, and transparent investor reporting. “Safe, Simple, Secured” describes the firm’s positioning and approach to risk management. It is not a guarantee of investment safety, income, liquidity, or principal repayment.
The firm’s alternative lending platform may also provide qualified borrowers with business-purpose financing across a broader set of use cases, including commercial real estate and certain operating-business financing needs. Those borrower financing products are distinct from the fund’s investor offering. Investors should not assume that every loan product offered through a lending platform is held by, collateralizes, or contributes returns to a particular investment fund. The applicable offering documents and fund disclosures should govern that determination.
Questions to Ask Before Committing Retirement Capital
Before making a private investment, an investor should request and review the current offering documents, subscription materials, risk disclosures, fee schedule, valuation policies, and investor reporting samples where available. The objective is not merely to confirm an expected return, but to understand the conditions under which that return may change or capital may be at risk.
Key questions include whether the investment is restricted to accredited investors, how the fund defines its lending mandate, what concentration limits or exceptions may apply, what events could reduce or delay distributions, and how conflicts of interest are addressed. It is also reasonable to ask how the manager approaches workouts, foreclosures, restructurings, and loan extensions when a borrower does not perform as expected.
Investors using self-directed IRAs or other retirement vehicles should also consider the administrative requirements, custody arrangements, prohibited-transaction considerations, and distribution needs associated with their specific situation. A qualified tax, legal, and financial adviser can help assess those issues. Nothing in an investment presentation or educational article should replace individualized advice.
Past performance, if presented in approved materials, does not guarantee future results. A disciplined manager, senior collateral position, and detailed underwriting process may help manage risk, but none removes the possibility of loss.
For retirement investors, the strongest decision is often the one made slowly: confirm eligibility, preserve adequate liquidity, understand the documents, and allocate only capital that can remain committed through the investment’s intended horizon.