Atlanta is not a single investment thesis. A stabilized multifamily property, an infill redevelopment, a suburban industrial asset, and a land-development project can respond very differently to the same local economic conditions. That distinction matters when evaluating why investors are moving to Atlanta, particularly for accredited investors considering private real estate credit rather than direct property ownership.
The relevant question is not whether Atlanta is “hot.” It is whether a specific loan is supported by durable collateral, a credible business plan, an experienced borrower, and underwriting assumptions that can withstand a range of outcomes. Location can improve the opportunity set. It does not replace disciplined credit analysis.
Why Investors Are Moving to Atlanta
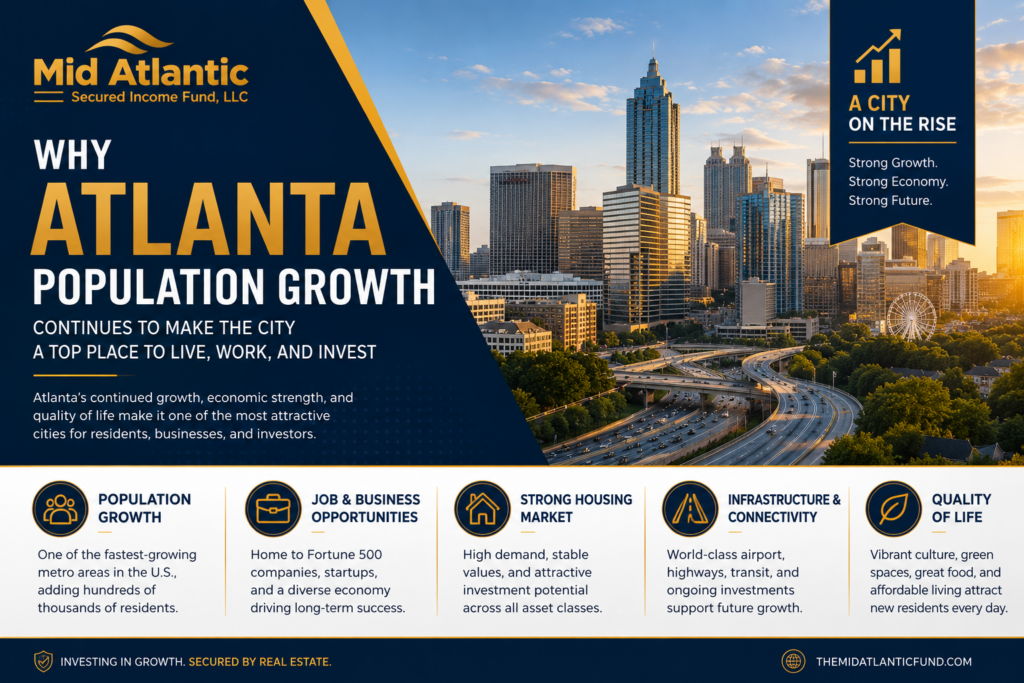
Atlanta continues to attract attention because it is a major Southeastern business center with a broad economic base, a large metropolitan footprint, and diverse real estate submarkets. For investors, that breadth can create a deeper pool of business-purpose financing needs across acquisition, renovation, redevelopment, construction, and commercial property transitions.
A large market can also offer more data points for underwriting. Comparable sales, lease activity, supply pipelines, property taxes, zoning requirements, and local demand drivers still require careful verification, but established markets often provide more information than thinly traded locations. Better information does not eliminate risk. It can, however, help a lender test assumptions rather than rely on a borrower’s projections alone.
Atlanta’s appeal is also highly submarket-specific. Employment nodes, transportation access, school districts, municipal rules, neighborhood-level supply, and the condition of competing inventory can materially affect collateral value and exit liquidity. A lender evaluating a property near a growing commercial corridor may reach a different conclusion than it would for a similar asset several miles away.
For private-credit investors, this is where senior-secured, first-position real estate lending can be relevant. The investment case is generally centered on the loan structure and collateral, not on capturing every increase in property value. A first-position lien may provide a defined legal claim against pledged real estate, subject to the terms of the loan documents and applicable law. It does not assure repayment, prevent a decline in collateral value, or guarantee a timely recovery if a borrower defaults.
A Market Story Is Not a Credit Decision
Real estate narratives often focus on migration, business formation, logistics, film production, or corporate expansion. Those trends may be worth studying, but they should remain inputs to diligence rather than conclusions. A strong regional story can coexist with oversupply in a particular property type, rising operating costs, delayed construction, or a borrower whose execution capacity is unproven.
The central underwriting questions are more concrete: What is the property worth under supportable assumptions? What is the borrower’s equity at risk? What is the repayment path? How long could that path take if the original plan is delayed? What costs, liens, permits, insurance requirements, or title matters could impair the lender’s position?
In Atlanta, as in any market, the quality of the collateral and the quality of the loan documents matter more than a headline about population or growth. A disciplined lender should evaluate the asset, sponsor, capital stack, valuation support, construction or renovation budget where applicable, and anticipated exit strategy. The analysis should include stress considerations, not only the base case.
For example, a renovation loan may depend on accurate scope, contractor oversight, permit timing, and realistic resale assumptions. A commercial bridge loan may depend on tenant retention, lease-up progress, or a refinance that remains available at maturity. Land and development lending may carry additional entitlement, infrastructure, absorption, and market-cycle risks. Each use case demands its own underwriting framework.
What Private Credit Can Offer – and What It Cannot
Private real estate credit may appeal to investors seeking income-oriented exposure that is structured differently from direct equity ownership. In a senior-secured lending strategy, the lender’s contractual position, collateral rights, and underwriting discipline are intended to place capital preservation at the center of the process.
That framing requires precision. “Secured” describes the presence of pledged collateral and the lender’s legal position. It does not mean that an investment is safe, guaranteed, liquid, or insulated from loss. Real estate collateral can decline in value, title or legal issues can arise, borrowers can default, and workout or foreclosure processes can be costly and time-consuming.
Private fund interests also involve risks distinct from individual loans. Depending on the offering, investors may not select each underlying investment, may have limited liquidity, and may bear management fees, expenses, conflicts of interest, concentration risk, valuation uncertainty, and the risk that distributions are reduced or not made. Offering documents, subscription materials, and periodic reports should be reviewed closely before making an allocation decision.
For eligible accredited investors, including self-directed IRA investors, family offices, RIAs, and institutions, suitability is not a box to check. It is a due-diligence process. Liquidity needs, portfolio concentration, investment horizon, risk tolerance, and the mechanics of holding a private investment all deserve attention. Investors should consult qualified tax, legal, and financial advisers regarding their individual circumstances.
Due Diligence for an Atlanta-Focused Credit Opportunity
An Atlanta opportunity should be evaluated at the loan level where information is available, and at the manager level when investing through a fund. The market may be attractive, but underwriting quality determines whether market opportunity is translated into a defensible credit decision.
Start with the collateral. Review how value was determined, the property’s current condition, its location within the relevant submarket, and the assumptions supporting any renovation, construction, lease-up, or disposition plan. Independent third-party reports can be useful, but their dates, scope, and assumptions should be examined rather than accepted at face value.
Then assess the borrower and repayment path. Borrower experience should be relevant to the proposed project, and liquidity, contingent obligations, existing liens, and execution history can matter as much as the proposed business plan. A repayment plan based solely on a future sale or refinance deserves particular scrutiny because capital-market conditions can change.
Finally, examine the manager’s process. Investors should understand who originates loans, who approves them, how exceptions are handled, how collateral is monitored, what reporting is provided, and how troubled loans are managed. Transparent reporting cannot remove risk, but it can help investors evaluate exposures and ask better questions.
Public data should be verified at the time of review. Depending on the issue under consideration, authoritative sources may include the U.S. Census Bureau for demographic and housing data, the Bureau of Labor Statistics for employment information, local county property records for parcel-level details, and municipal planning departments for zoning and permit information. Source dates matter because market conditions and development pipelines can change quickly.
Keep Borrower Financing Separate From Fund Investing
Atlanta’s financing demand can be relevant to qualified borrowers as well as investors, but these are separate decisions. A borrower seeking a commercial bridge loan, acquisition financing, construction financing, renovation or redevelopment capital, site development lending, or another business-purpose financing product should expect underwriting based on the specific transaction, collateral, documentation, and repayment plan.
Not every financing product offered through an alternative lending platform is necessarily held by, collateralizes, or generates returns for a private investment fund. Qualified borrowers should review the applicable financing process and documentation. Investors should rely on the fund’s current offering documents to understand the fund’s investment mandate, risks, fees, liquidity provisions, and portfolio construction.
Mid Atlantic Secured Income Fund’s positioning – Safe, Simple, Secured – is best understood as a commitment to a disciplined approach centered on senior-secured, first-position real estate lending, collateral quality, and transparent investor communication. It is not a promise of investment results or protection from loss.
Atlanta may provide a compelling setting for real estate credit, but the market should be the beginning of the analysis, not the end. The more useful investor question is whether the collateral, structure, and underwriting remain credible when the optimistic assumptions are tested.