A Southeast market can look compelling on a population-growth chart and still present a weak lending opportunity. For accredited investors evaluating the top Southeast markets for real estate investing, the more useful question is not simply where growth is occurring. It is whether a specific property, sponsor, capital structure, and exit plan can support senior-secured credit through changing market conditions.
For a real estate credit strategy, market selection is a risk-control exercise. Demand drivers matter, but so do the depth of buyer demand, competing supply, local entitlement conditions, insurance exposure, construction costs, and the liquidity of comparable properties when a loan must be refinanced or sold. A disciplined underwriting process evaluates those factors property by property rather than treating a state or metro area as a single investment thesis.
What Makes a Southeast Market Attractive for Real Estate Credit
The Southeast includes large, economically diverse metros alongside smaller growth corridors. That variety can create opportunities, but it also makes broad regional assumptions unreliable. A market with healthy job formation may have pockets of excess multifamily supply. A fast-growing suburban county may have limited transaction history for a specialized commercial property. A coastal location may require more intensive review of insurance availability, flood exposure, and replacement costs.
For senior-secured, first-position real estate lending, collateral quality begins with the asset itself: location, condition, use, sponsor business plan, and realistic path to stabilization or sale. It also depends on the loan structure, borrower equity, repayment source, title position, and the ability to manage a workout if the original plan does not perform as expected.
At Mid Atlantic Secured Income Fund, this distinction is central to the underwriting mindset. “Safe, Simple, Secured” is a positioning principle, not a promise that an investment is safe or free of loss. Private credit investments involve risk, including credit risk, real estate market risk, borrower default, valuation risk, and limited liquidity. Investors should review applicable offering documents and consult qualified legal, tax, and financial advisers before making an investment decision.
Top Southeast Markets for Real Estate Investing: A Credit View
The following markets merit attention because they combine scale, varied demand sources, or established commercial real estate activity. They are not a ranking, a recommendation to invest, or a substitute for loan-level diligence. Conditions can change materially by neighborhood, property type, and financing cycle.
Charlotte, North Carolina
Charlotte offers a broad employment base, a substantial financial-services presence, and a metro footprint that supports multiple property types. For real estate lenders, its appeal is not confined to a single sector. Residential infill, industrial-adjacent sites, select neighborhood retail, and well-located commercial redevelopment can each present different underwriting opportunities.
The trade-off is that growth and competition can encourage aggressive assumptions. Underwriting should test whether projected rents, absorption, construction budgets, and sales comparables remain credible if demand moderates. A property in an established submarket with multiple viable exit paths may warrant a different view than a more speculative project on the edge of new development.
Raleigh-Durham, North Carolina
Raleigh-Durham benefits from an economy shaped by research, higher education, technology, health care, and government-related activity. Its long-term demand story is often attractive to sponsors pursuing housing, mixed-use, and commercial projects near established employment nodes.
Still, an institutional demand narrative does not replace collateral analysis. Development pipelines, local zoning, rental competition, and the timing of lease-up can meaningfully affect project outcomes. For construction or redevelopment loans, lenders should examine sponsor experience with the exact asset type and submarket, not merely experience elsewhere in the region.
Atlanta, Georgia
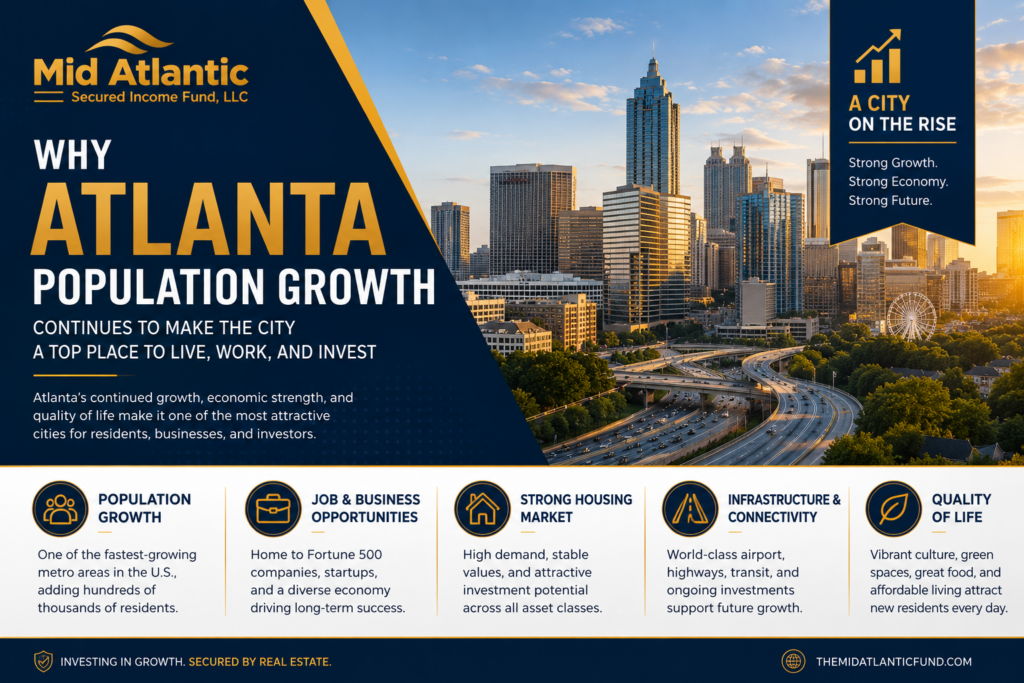
Atlanta remains one of the Southeast’s most consequential real estate markets because of its scale, transportation infrastructure, corporate presence, and geographic breadth. It can offer a wide range of opportunities, from infill residential projects to industrial, mixed-use, and commercial repositioning.
Scale also brings dispersion. Market conditions may differ sharply across intown neighborhoods, suburban business districts, and logistics corridors. A lender should avoid relying on metro-wide comparables when the collateral’s value depends on a narrow local buyer pool. Clear title, practical access, functional design, and a supportable valuation are often more important than a favorable headline about the metro.
Nashville, Tennessee
Nashville has attracted sustained attention from residents, employers, developers, and capital providers. Its hospitality, health care, education, entertainment, and professional-services activity can support a range of property uses. For qualified borrowers, that can create business-purpose financing needs tied to acquisition, renovation, redevelopment, or construction.
The underwriting challenge is separating durable demand from pricing that already reflects optimistic expectations. In active markets, land costs, contractor availability, and competing inventory can narrow a project’s margin for error. Senior lenders should focus on conservative assumptions, documented sources and uses, completion risk, and realistic refinance or disposition scenarios.
Greenville-Spartanburg, South Carolina
Greenville-Spartanburg is often evaluated through the lens of manufacturing, logistics, and its growing regional connectivity. The area can be relevant for industrial-related development, housing demand connected to employment centers, and smaller commercial projects that may not fit a national institutional lender’s standardized profile.
Smaller and mid-sized markets require particular attention to liquidity. Comparable sales may be less abundant, specialized assets may have fewer buyers, and a sponsor’s stated exit may depend on conditions that are difficult to verify. That does not eliminate opportunity. It raises the value of conservative valuation work, sponsor diligence, and a first-position collateral structure designed for downside protection.
Orlando and Tampa Bay, Florida
Central and West Florida continue to draw attention for residential growth, business formation, and tourism-related economic activity. Orlando and Tampa Bay are large enough to support diverse real estate activity, including infill housing, renovation, commercial projects, and select redevelopment opportunities.
Florida underwriting has additional considerations. Property insurance costs and availability, wind and flood exposure, building-code requirements, and condominium or association-related issues can affect both operating costs and resale liquidity. These factors should be addressed early, with current documentation, rather than treated as secondary diligence items after the loan is structured.
The Market Is Only One Layer of the Decision
A favorable metro cannot cure weak sponsorship, unclear title, poor construction controls, or an unrealistic exit strategy. Likewise, a smaller market should not be dismissed solely because it lacks national headlines if the collateral is well understood, the borrower has demonstrated execution capability, and the repayment plan is credible.
For a private real estate credit fund, investors should ask how the manager evaluates market concentration, borrower concentration, property type exposure, loan maturity profiles, valuation practices, servicing, and workout authority. They should also understand the fund’s liquidity terms, fees, conflicts of interest, and the limits of any reporting. Private fund interests are generally illiquid and may not be appropriate for every accredited investor or retirement account.
Transparent reporting is especially important because private-credit valuations and realized outcomes may develop over time. Past performance, if presented in offering materials, does not guarantee future results. Investors should evaluate current documents rather than relying on generalized market commentary.
Separate the Investor Decision From the Borrower Financing Need
Qualified borrowers may seek business-purpose financing for an acquisition, renovation, redevelopment, construction project, site development, lot acquisition, or fix-and-flip project. The broader lending platform may also consider other business-purpose financing categories, subject to underwriting, documentation, availability, and applicable requirements.
That borrower financing activity should not be assumed to be held by, collateralize, or generate returns for any particular investment fund. The investor decision concerns the specific fund offering and its governing documents. The borrower decision concerns the proposed financing transaction, its collateral, business purpose, repayment source, and negotiated terms.
A thoughtful approach to Southeast real estate begins with a market map, but it should end with disciplined loan-level diligence. The strongest opportunity is often not the fastest-growing location. It is the transaction where collateral, structure, sponsor capability, and a realistic exit plan remain aligned when the market becomes less forgiving.