A vacant unit, an unexpected repair, or a delayed sale can quickly remind a property owner that rental real estate is not automatically passive. For accredited investors, real estate passive income investing may also take a different form: lending against real estate rather than owning, operating, and eventually selling the property itself. That distinction changes the source of return, the investor’s place in the capital structure, and the due diligence required before capital is committed.
Private real estate credit can be a useful area to evaluate for investors seeking current-income potential with an emphasis on collateral and underwriting discipline. It is not a substitute for cash, and it carries meaningful risks, including illiquidity and the possibility of loss. Its potential value lies in understanding exactly what is being financed, how the lender is protected, and what happens when a loan does not perform as expected.
Passive Income Starts With the Investment Structure
The phrase “passive income” describes the investor’s level of day-to-day involvement, not the absence of risk. A limited partner in a real estate equity transaction, a direct owner of a rental home, and an investor in a private credit fund may all describe their investments as passive. Yet their economics and responsibilities are materially different.
With direct property ownership, income may depend on occupancy, rent collection, operating expenses, capital improvements, financing costs, and the eventual sale of the asset. The investor participates in both the potential upside and downside of property operations and value changes. Even when a professional manager is hired, the owner remains exposed to operating decisions and may face capital calls or unplanned expenses.
A real estate credit investor is generally positioned differently. The primary contractual obligation is repayment of principal and interest by the borrower, subject to the loan documents. Where the loan is secured by real estate, the property serves as collateral. The investment thesis is typically centered less on maximizing property appreciation and more on identifying loans with an appropriate collateral position, a credible repayment path, and documentation that supports enforcement rights if necessary.
That does not make credit investing passive in the sense of requiring no judgment. It makes the investment operationally passive for the investor when a manager originates, underwrites, services, and monitors loans. The investor’s responsibility shifts to selecting the manager and understanding the governing offering documents.
How Real Estate Passive Income Investing Works in Private Credit
In a private credit structure, a fund may pool capital from eligible investors and deploy it according to its stated investment strategy. For a strategy focused on senior-secured, first-position real estate lending, the fund may make loans that are secured by a first lien or comparable senior claim against a real estate asset, subject to the specific transaction documents and applicable law.
First position matters because capital structure influences the order of repayment when a borrower defaults or collateral is liquidated. A senior lender may have priority over junior creditors with respect to the pledged collateral. Priority is not a guarantee of full recovery. Property values can decline, enforcement can take time, senior claims can be subject to costs and legal complexities, and collateral proceeds may be insufficient to cover all obligations.
The income profile of a credit strategy is also different from equity ownership. Rather than relying chiefly on rental cash flow and appreciation, the lender seeks contractual payments under the loan. Borrower repayment may come from a property sale, a refinance, completed construction, stabilized operations, or another documented source. Each repayment path deserves scrutiny because a loan that appears well secured can still be vulnerable if the exit strategy is weak.
For investors, the key question is not simply whether a loan is backed by real estate. It is whether the underwriting process has reasonably evaluated the property, borrower, loan structure, market conditions, and realistic options if the original repayment plan changes.
Collateral Quality Is Only One Layer of Protection
Real estate collateral can provide an identifiable asset base, but collateral alone is not a complete risk control. A disciplined lender evaluates the broader transaction. The property type, condition, title position, insurance requirements, intended use of proceeds, borrower experience, and local market conditions can each affect credit quality.
A renovation loan, for example, may depend on a borrower completing a defined scope of work and selling or refinancing the property. A bridge loan may depend on a time-sensitive transition in ownership or financing. Construction and development lending may introduce additional risks tied to permits, contractors, cost changes, timing, and completion. These are not interchangeable credit exposures, even when each is secured by real estate.
Sound underwriting also considers the downside case. If the project is delayed, if demand softens, or if refinancing markets become less available, can the borrower continue to perform? If not, what are the lender’s rights, remedies, and likely recovery process? No underwriting standard can eliminate uncertainty, but a disciplined process should identify where uncertainty is concentrated and avoid treating an optimistic business plan as collateral.
What Investors Should Review Before Committing Capital
Private funds are often less liquid and less standardized than publicly traded securities. An investor should therefore treat due diligence as a central part of the decision, not a formality after an attractive income objective has been presented.
Begin with the offering documents. These materials should explain the fund’s investment mandate, investor eligibility, fees and expenses, conflicts of interest, valuation practices, liquidity restrictions, distribution policy, risk factors, and the manager’s authority. The terms of the offering documents govern, and an investor should not rely on general marketing language to fill in missing details.
Next, examine how the manager defines and applies its lending discipline. Useful questions include whether the strategy is focused on senior positions; how collateral is evaluated; how loans are monitored after closing; who makes credit decisions; and what procedures apply when a borrower misses a payment or requests a modification. A transparent manager should be able to describe its process without suggesting that every loan will perform as expected.
Reporting quality matters as well. Investors should understand what information they can expect to receive, how often it is delivered, and how the manager communicates material developments. Clear reporting does not eliminate risk, but it supports informed oversight and helps investors assess whether portfolio activity remains consistent with the stated strategy.
Finally, assess fit. Private real estate credit may be unsuitable for capital that could be needed on short notice. An investor should consider liquidity needs, concentration, time horizon, risk tolerance, and the potential effect of fees and expenses on investment outcomes. Self-directed IRA investors, family offices, RIAs, and institutions may also have account-level, fiduciary, tax, or operational considerations that warrant review with qualified advisers. This is not individualized investment, tax, or legal advice.
Fund Investing and Borrower Financing Are Separate Decisions
A private credit fund’s investor offering should be evaluated separately from a lender’s borrower-facing financing platform. A lending platform may offer qualified businesses and real estate borrowers a range of business-purpose financing options, including bridge, acquisition, renovation, construction, redevelopment, land development, lot acquisition, fix-and-flip, inventory, purchase-order, receivables, litigation, automotive, and working-capital financing.
Those products may serve different borrower needs and involve different collateral, documentation, and underwriting considerations. They should not be assumed to be fund investments, fund collateral, or sources of returns for fund investors unless the applicable offering documents and approved disclosures specifically state that relationship.
For a real estate borrower, the appropriate inquiry is whether the financing structure suits a defined business purpose, a documented repayment plan, and the risks of the project. For an investor, the inquiry is whether the fund’s stated portfolio strategy, controls, liquidity profile, and disclosures meet the investor’s own due-diligence standards. Combining these journeys can obscure the risks in both.
The Trade-Off Behind Current-Income Potential
The appeal of senior-secured real estate credit is understandable: it can offer exposure to real estate-backed lending without the operating burden of direct ownership. But the trade-off is that investors place capital with a private manager and may have limited ability to exit quickly. They also depend on underwriting quality, servicing discipline, collateral realization, and the legal enforceability of loan documents.
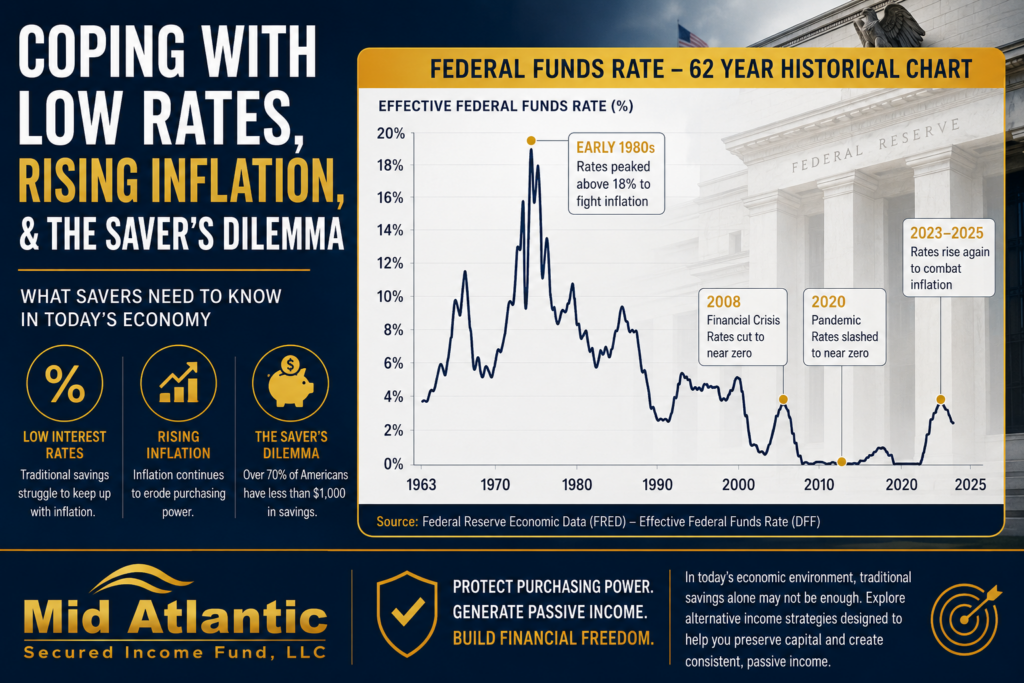
Market conditions can affect borrowers’ ability to sell, refinance, lease, or complete projects. Interest-rate changes, construction costs, insurance costs, local supply and demand, and lender availability can all influence repayment outcomes. Past performance, if presented in approved materials, does not guarantee future results.
Mid Atlantic Secured Income Fund’s positioning around capital preservation objectives, senior-secured first-position real estate lending, and transparent reporting reflects the questions disciplined investors should ask of any private credit opportunity. The relevant standard is not whether an investment sounds passive. It is whether its risks, protections, limitations, and role in a broader portfolio are clearly understood before capital is committed.
A constructive next step is to read the applicable offering documents carefully, ask precise questions about liquidity and risk management, and involve qualified advisers where appropriate. Patient due diligence is often the most practical form of passive investing discipline.