A property can look compelling on a broker’s summary and still present an unacceptable credit risk. Commercial real estate trends matter because they change the assumptions beneath a loan: whether cash flow can support debt service, whether a borrower has a credible path to refinance or sell, and whether collateral could retain value under less favorable conditions.
For accredited investors evaluating private real estate credit, the useful question is not which property sector will produce the next headline. It is whether a specific loan has been structured and underwritten to account for uncertainty. For qualified borrowers, the same environment makes complete documentation, realistic business plans, and clear exit strategies more important.
Commercial Real Estate Trends Are Credit Trends
Real estate headlines often focus on property values, transaction volume, or a single challenged sector. Credit analysis is more practical. A lender must assess how changing conditions affect the property, the sponsor, the loan structure, and the expected repayment source.
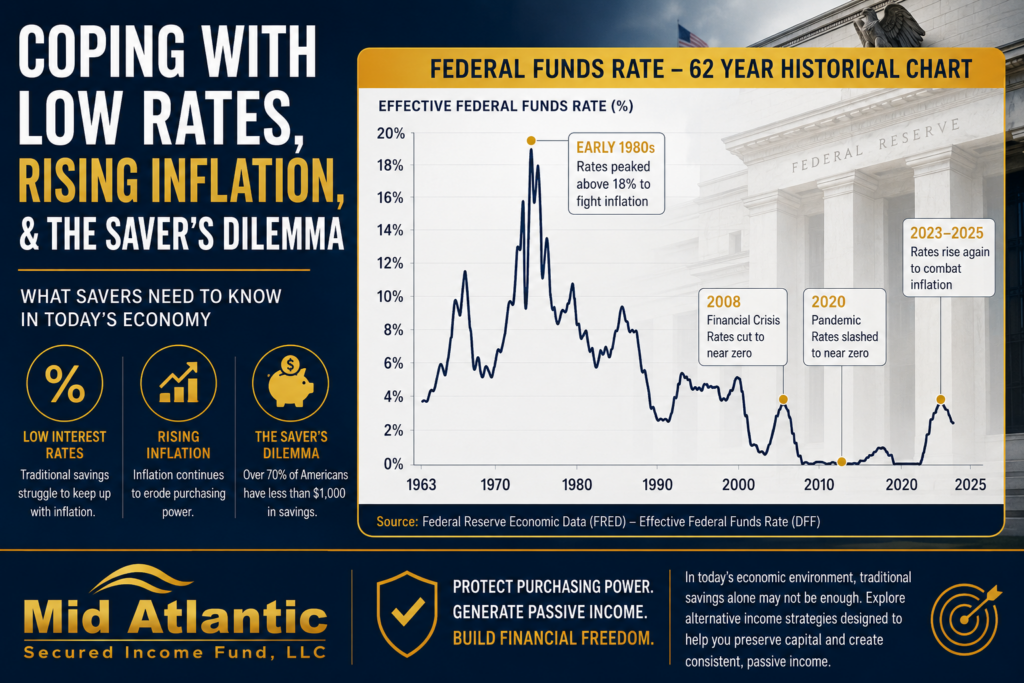
Interest-rate sensitivity remains a central consideration. A loan that performed when borrowing costs were lower may face pressure at maturity if replacement financing is more expensive or less available. That does not mean every existing loan is impaired. It means underwriting should examine debt-service capacity under reasonable stress, the maturity schedule, lease rollover, and the borrower’s ability to contribute additional capital if needed.
Valuation uncertainty requires equal attention. Commercial property values are not determined by a single data point. They reflect property income, operating expenses, tenant quality, market rents, capitalization assumptions, physical condition, and buyer demand. When comparable transactions are limited or conditions are moving quickly, a disciplined lender should avoid treating an appraisal as a permanent answer. Collateral quality and a conservative view of liquidity matter most when an exit takes longer than planned.
For a senior-secured, first-position real estate lender, the key issue is not predicting the market perfectly. It is building a margin of discipline around what can go wrong.
Refinancing Risk Has Moved to the Forefront
Many commercial loans depend on a future refinancing, sale, or project completion event. That makes the exit strategy more than a closing-file formality. It is a core underwriting assumption.
A credible refinance exit considers the property’s stabilized income, the anticipated maturity date, the borrower’s track record, the condition of the capital markets, and the availability of a realistic financing alternative. A sale exit should be evaluated against the property’s likely buyer pool, local demand, required repairs, and the time needed to complete a transaction.
The trade-off is straightforward. A shorter-duration loan may limit exposure to a long-dated business plan, but it can also concentrate refinancing risk if the borrower needs more time than expected. A longer term may provide more operating runway, yet it also exposes the lender to a longer period of market and execution risk. The appropriate structure depends on the asset, sponsor, cash flow, and repayment plan.
Extension Requests Are an Underwriting Event
When a borrower requests additional time, the lender should revisit the facts rather than rely on the original approval. Has construction progressed? Has leasing met expectations? Are taxes, insurance, and senior obligations current? Has the business plan changed? Is there new capital in the transaction?
An extension can be reasonable in some circumstances, but it should be supported by updated diligence, not assumed. This is one reason transparent reporting and active loan monitoring are meaningful to investors in private credit strategies.
Property Type Alone Does Not Determine Risk
Office, industrial, retail, multifamily, hospitality, medical, and land each have distinct demand drivers. Yet broad labels can conceal the factors that matter most to a lender.
An office asset may have durable tenancy and manageable lease expirations, or it may face costly re-leasing and capital needs. A multifamily property may have recurring revenue, but expenses, local supply, maintenance requirements, and regulatory constraints can alter net operating income. Industrial demand can be favorable in one location while a particular building remains functionally obsolete. Land may offer development potential, but it generally depends more heavily on entitlement, infrastructure, financing, and market timing than a cash-flowing property.
The underwriting question is therefore asset-specific: What supports value today, what threatens it, and how durable is the repayment source if the original plan changes? Quality collateral is not simply a desirable property type. It is a property with identifiable value drivers, marketability, and a fact-based path to disposition if necessary.
Construction and Redevelopment Require More Than a Budget
Construction, renovation, and redevelopment financing introduce risks that are less prominent in stabilized assets. Cost overruns, contractor performance, permitting delays, material availability, lease-up risk, and changes in market demand can all affect a project’s economics.
A disciplined review considers the scope of work, sponsor equity, construction budget, contingency planning, contractor documentation, draw controls, insurance, permits, and the realism of the completion and exit plan. It should also consider whether the completed asset serves a market need that can be supported by evidence rather than optimism.
For borrowers, clear records are part of the financing process. Incomplete plans, unsupported budgets, unclear ownership structures, or unrealistic timelines can create avoidable friction. A well-prepared borrower presents a coherent story supported by documentation, not just a favorable pro forma.
What Investors Should Evaluate in Private Real Estate Credit
Private credit may offer a different set of considerations than publicly traded real estate securities, but it is not a substitute for cash and should not be evaluated as if liquidity were assured. Interests in a private fund can be illiquid, may be subject to transfer restrictions and other limitations, and involve the risk of loss. Investors should review the applicable offering documents carefully and consider whether the investment fits their objectives, time horizon, liquidity needs, and risk tolerance.
For eligible accredited investors, due diligence should focus on the investment structure as well as the underlying lending philosophy. Relevant questions include whether the strategy emphasizes senior-secured, first-position real estate loans; how collateral is evaluated; how concentration is managed; how loans are monitored; what fees and conflicts may apply; and how investor reporting addresses portfolio activity and risks.
It is also appropriate to understand the difference between stated objectives and realized results. Capital-preservation objectives and disciplined underwriting standards describe an approach, not an assurance of outcomes. Past performance, where presented in approved materials, does not guarantee future results.
At Mid Atlantic Secured Income Fund, the positioning of Safe, Simple, Secured is intended to describe a disciplined, collateral-focused approach to private real estate credit, not to eliminate investment risk. Investors should rely on current offering materials and consult qualified legal, tax, and financial advisers before making an investment decision.
Borrower Financing Is a Separate Evaluation
Qualified borrowers may seek business-purpose financing for commercial bridge loans, acquisitions, construction, renovations, redevelopment, land development, lot acquisition, or other operating needs. The broader lending platform may also evaluate certain business-purpose financing requests involving receivables, purchase orders, inventory, automotive businesses, or working capital.
These borrower financing products must be evaluated on their own underwriting criteria. Eligibility, collateral requirements, documentation, use of proceeds, and terms vary by transaction. Availability of a financing product does not mean it is held by, collateralizes, or generates returns for the investment fund.
Borrowers can improve the quality of an initial conversation by preparing entity documents, ownership information, property details, current financials, a clear use-of-proceeds explanation, project budgets where applicable, and a defined repayment plan. A financing request is strongest when the requested capital, business purpose, collateral, and exit strategy align.
A Practical Framework for Changing Conditions
Commercial real estate trends will continue to influence borrowing costs, valuation assumptions, property operations, and transaction timing. The disciplined response is not to chase broad market narratives or dismiss them. It is to test each transaction against the conditions that could affect repayment.
For investors, that means examining underwriting standards, seniority in the capital stack, collateral quality, reporting practices, fees, risks, and liquidity constraints. For borrowers, it means presenting a documented plan that can withstand questions about costs, timing, cash flow, and the exit.
The most useful next step is a measured one: review the governing documents, verify the assumptions that matter to the transaction, and make decisions only after the risks are understood alongside the opportunity.