Renovation financing is often decided before the first wall comes down. A project can have a credible business plan, an experienced sponsor, and a desirable property, yet still face avoidable pressure if the scope, construction budget, collateral, and repayment strategy do not align. For qualified real estate borrowers, financing should support a defined redevelopment plan rather than compensate for an incomplete one.
That distinction matters to private credit lenders and to investors evaluating private real estate credit. A renovation loan is not simply capital for improvements. It is a credit decision tied to the property, the borrower’s execution capacity, the project’s documentation, and the lender’s assessment of downside scenarios.
What renovation financing is designed to support
Renovation financing generally serves business-purpose projects in which a borrower intends to improve, reposition, repair, or redevelop real estate. The intended work may range from targeted upgrades that improve usability to substantial rehabilitation that changes the property’s condition, tenant appeal, or market positioning.
The financing structure should reflect the real purpose of the project. A borrower acquiring a property with a defined renovation plan faces different considerations than an owner improving an existing asset. Likewise, a short-duration property repositioning requires a different repayment plan than a redevelopment intended to transition into stabilized, longer-term financing.
A disciplined lender will look beyond the headline construction budget. The questions are practical: What work is necessary to achieve the stated business plan? Who will complete it? Is the budget sufficiently documented? What approvals, permits, inspections, or contractor agreements may affect the timeline? How will the borrower address cost overruns or delays?
These are not merely administrative questions. They help determine whether the financing request and the project plan are consistent with each other.
Start with the exit, not the loan request
Borrowers sometimes begin by asking how much capital may be available. A more useful starting point is the anticipated repayment source. In renovation financing, repayment may depend on a sale, a refinance, operating cash flow, or another documented source of capital. Each path carries different execution risks.
A sale-based strategy may be sensitive to market demand, buyer financing conditions, property completion, and the final quality of the work. A refinance strategy depends on the property reaching a condition and income profile that another lender will accept, while also depending on the borrower’s broader financial position. An operating-cash-flow strategy requires careful attention to lease-up, occupancy, expenses, and property management.
No exit strategy is automatic. Borrowers should test the plan against reasonable delays, higher costs, and a slower-than-expected disposition or stabilization period. The goal is not to assume a negative outcome. It is to understand what decisions and reserves may be needed if the original timeline changes.
The construction budget needs more than one number
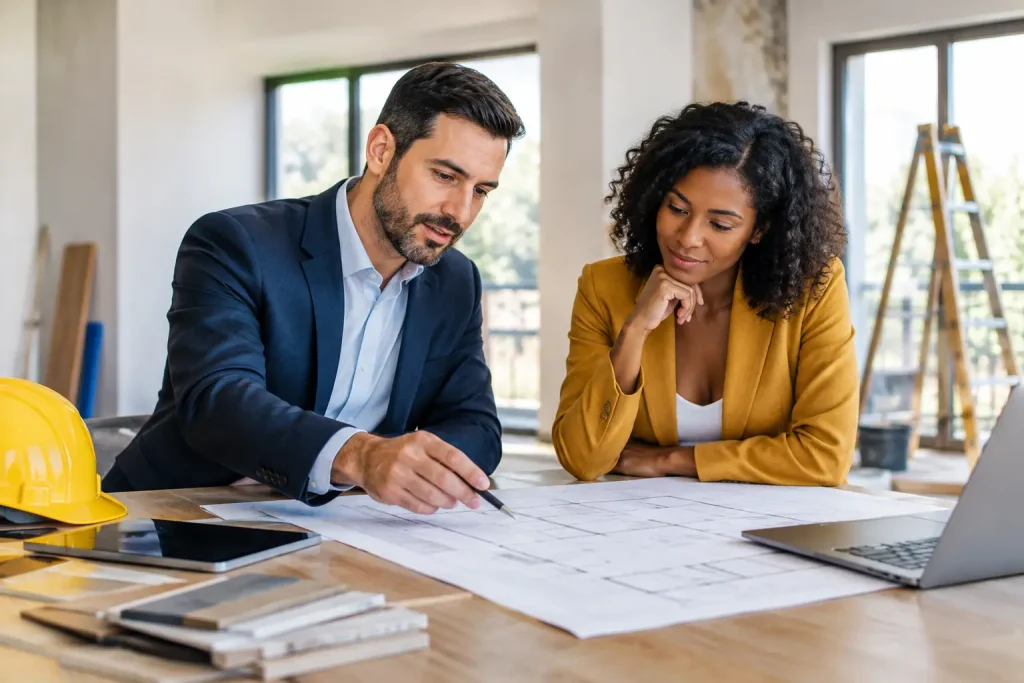
A construction budget should identify the major work categories, expected labor and material costs, professional fees, permits, insurance, carrying costs, and an appropriate contingency approach. Supporting documentation may include contractor bids, scope-of-work narratives, invoices, plans, schedules, and evidence of required approvals.
The strongest budgets are specific enough to be reviewed and managed. A single all-in estimate may be useful as an early planning figure, but it provides limited insight into sequencing, cost controls, or the consequences of a delayed component. Clear documentation also gives the borrower a better basis for communicating with contractors, equity partners, and prospective lenders.
Borrowers should be equally candid about items that remain uncertain. Concealed conditions, utility issues, municipal requirements, supply disruptions, and contractor availability can change a project after work begins. A lender may view transparent identification of these issues more favorably than an unrealistically clean budget.
Collateral quality and borrower execution both matter
In business-purpose real estate lending, the property is a central part of the credit analysis, but it is not the only consideration. Collateral quality involves location, condition, marketability, property type, existing liens, title matters, insurance, and the relationship between the asset and the proposed renovation plan.
Borrower execution matters because a renovation is an operating process as well as a real estate transaction. Relevant considerations may include prior project experience, contractor oversight, liquidity available for project needs, organizational structure, ownership records, and the borrower’s ability to provide timely reporting and documentation.
This does not mean every qualified borrower must fit one profile. An experienced developer, a builder, and a real estate investor with a focused repositioning plan may present different strengths and risks. The appropriate structure depends on the facts of the transaction, not a generic formula.
For qualified borrowers, preparation can improve the quality of the financing conversation. A complete request often includes the purchase or ownership information, a clear scope of work, budget detail, contractor information, project schedule, property photos or plans where relevant, and a realistic repayment strategy. Lenders may request additional financial, legal, title, insurance, and entity documentation as part of underwriting.
Renovation financing is not a substitute for project controls
Financing cannot correct a weak contractor relationship, missing permits, unclear ownership, or an unsupported property valuation. It can, however, provide a framework that encourages better planning. Construction monitoring, documentation requirements, and conditions tied to project progress can help create accountability for both the borrower and lender.
Those controls also involve trade-offs. More documentation and oversight may require additional borrower attention, particularly on projects with multiple contractors or changing schedules. Yet a structure that requires timely visibility into the project can reduce surprises that become more difficult to address later.
Borrowers should ask direct questions before pursuing any financing product: What documentation will be required? How are project changes handled? What events could affect future advances, if applicable? What reporting is expected? What fees, prepayment provisions, default terms, and obligations are described in the loan documents? The answers should be reviewed carefully with qualified legal, tax, and financial advisers.
What investors should separate from borrower financing
Private real estate credit may be relevant to accredited investors seeking to evaluate income-oriented alternatives, but a borrower financing product and an investment offering are not the same thing. A platform may offer qualified borrowers renovation and redevelopment loans alongside other business-purpose financing products. That does not mean each loan is held by, collateralizes, or generates returns for a private investment fund.
Investors evaluating a private credit fund should review the applicable offering documents to understand the fund’s stated strategy, portfolio parameters, fees, liquidity limitations, risks, reporting practices, and eligibility requirements. They should also determine whether the strategy emphasizes senior-secured, first-position real estate lending and how underwriting, collateral review, and concentration management are addressed in the governing materials.
Capital preservation objectives and disciplined underwriting are meaningful considerations, but they do not eliminate risk. Private investments can be illiquid, may involve loss of principal, and may not be appropriate for every investor. Past performance does not guarantee future results. Accredited investors, including self-directed IRA investors, family offices, and RIAs, should conduct independent due diligence and consult qualified advisers regarding their individual circumstances.
Mid Atlantic Secured Income Fund’s positioning of Safe, Simple, Secured reflects an emphasis on disciplined real estate credit, collateral quality, and transparent investor communication. It is not a guarantee of investment outcomes or a statement that every financing opportunity is part of the fund’s portfolio.
A disciplined next step for borrowers
Before seeking renovation financing, organize the transaction as though a third party will need to understand every major assumption. Reconcile the scope with the budget, the budget with the schedule, and the schedule with the repayment plan. Identify the documents that support each conclusion and the contingencies that may require additional attention.
For a qualified borrower, that preparation can lead to a more productive underwriting process and a clearer project plan. For an investor, the same discipline offers a useful lens for evaluating private real estate credit: understand the collateral, understand the structure, and understand the risks before committing capital.