A commercial development loan is not simply financing for a building project. It is capital advanced against a plan that must hold together through entitlement, construction, leasing or sale, and repayment. For qualified borrowers, the central question is whether the project has a credible path from raw land, redevelopment, or construction activity to a completed asset with a defined exit.
That distinction drives underwriting. A lender is assessing more than the property’s current condition. It is assessing the borrower’s control of the site, the quality of the development plan, the construction budget, the parties responsible for execution, the proposed collateral, and the source of repayment. A well-prepared request recognizes those questions early and presents the project with documentation that can withstand scrutiny.
What Commercial Development Loans Are Designed to Finance
Commercial development loans can support projects that create, reposition, or prepare real estate for a business purpose. Depending on the transaction, proceeds may be used for land acquisition, site preparation, horizontal improvements, vertical construction, redevelopment, or the acquisition of finished lots. The precise use of proceeds matters because it affects the construction timeline, collateral profile, required permits, and repayment strategy.
A project with approved plans and established utility access presents a different underwriting profile from land still moving through zoning and entitlement. Likewise, renovating an existing commercial building differs from constructing a new asset from the ground up. Neither is inherently better, but each has distinct risks, documentation needs, and contingency considerations.
Development financing is often structured around project milestones rather than a single unrestricted advance. Lenders may review progress, completed work, invoices, inspections, and updated budgets before releasing additional capital. This approach is intended to keep loan proceeds connected to the stated business purpose and to provide visibility into construction performance.
The Core Underwriting Questions
Disciplined underwriting begins with the property, then expands to the borrower and the execution plan. The lender needs to understand what exists today, what the borrower intends to create, and why the completed project should support repayment.
Site control, entitlement, and collateral
The borrower should be able to document ownership, a purchase contract, or another enforceable form of site control. Title information, surveys, environmental reports when applicable, zoning materials, plans, permits, and development agreements can all be relevant. Gaps in these items do not automatically end a financing discussion, but they should be identified directly rather than treated as minor details.
Collateral quality is especially important in development lending. A first-position lien on real estate may be a central protection in a senior-secured structure, but collateral value can change as a project advances or encounters delays. The lender will consider the property’s present condition, the feasibility of the proposed improvements, marketability, and any existing liens or obligations that could affect priority.
Sponsor capability and alignment
Development is an execution business. A borrower’s experience with similar property types, project sizes, construction scopes, and local approval processes can materially affect how a lender evaluates the request. The review may include prior project history, organizational structure, liquidity, credit considerations, litigation history, contractor relationships, and the borrower’s own capital committed to the transaction.
Experience alone is not a substitute for a complete plan. A capable sponsor can still face an underfunded budget, a weak contractor agreement, or an unrealistic sale or lease assumption. Conversely, a newer sponsor may need to provide stronger third-party support, more detailed documentation, or additional guarantees, subject to the lender’s policies and the transaction structure.
Budget discipline and construction oversight
A credible development budget separates hard costs, soft costs, site work, financing costs, insurance, reserves, and contingencies. It should also identify which items are fixed, which remain estimates, and which are dependent on approvals or third-party pricing. Understated costs are a common source of pressure later in a project, particularly when changes to plans, materials, labor, or utilities arise.
The construction contract deserves the same attention as the budget. Lenders may review the scope of work, payment schedule, contractor credentials, insurance, lien protections, and procedures for change orders. Borrowers benefit from having a clear method for reporting budget changes before they become capital shortfalls.
Repayment is not an afterthought
Every commercial development loan needs a defined repayment path. That may be a sale of the completed property, a refinance after stabilization, the sale of individual lots or units where permitted, or operating cash flow from a completed and leased asset. The proposed exit should be grounded in the project’s timing, market position, and available documentation.
A refinance-dependent plan requires particular care. Future financing conditions, appraisal conclusions, occupancy, and borrower qualification can differ from initial expectations. A sale strategy also carries timing and pricing risk. Underwriting should consider how the project may perform if the exit takes longer than anticipated or if costs rise before completion.
Documentation That Strengthens a Loan Request
The most productive borrower conversations start with organized materials. A lender generally needs enough information to evaluate the asset, the sponsor, the scope of work, and the repayment plan. That often includes entity documents, financial statements, a project narrative, purchase or ownership documents, title and survey information, plans and permits, construction budgets, contractor agreements, a sources-and-uses schedule, and evidence supporting the proposed exit.
The goal is not volume for its own sake. It is consistency. The budget should match the plans. The requested proceeds should match the sources-and-uses schedule. The proposed timeline should align with entitlement status, construction sequencing, and the exit plan. Where an assumption is preliminary, a borrower should label it as such and explain what remains to be verified.
Transparency can also help when a project has complications. Environmental remediation, zoning uncertainty, tenant issues, construction disputes, or prior liens should be disclosed early. These issues may affect the structure, timing, or availability of financing, but discovering them late can create greater difficulty for all parties.
Development Financing Is Different From Permanent Financing
Permanent commercial real estate financing generally relies on an operating asset with established income and a more stable value profile. Development financing supports a period when the property may generate limited income, require substantial work, or depend on future approvals and construction completion.
That difference can make development loans more complex. The lender may place greater weight on project controls, borrower experience, construction reporting, collateral priority, and the feasibility of the exit. Borrowers should not assume that a strong completed-value estimate alone answers these concerns. The path to that value matters.
For some projects, a commercial bridge loan, acquisition financing, renovation or redevelopment financing, or site and land development lending may be more appropriate than a conventional construction structure. The suitable product depends on the asset, use of proceeds, documentation, and repayment plan. Eligibility and terms vary by transaction, and an initial discussion is not a commitment to lend.
A Separate Consideration for Private Credit Investors
Commercial development loans may also be relevant to accredited investors evaluating private real estate credit, but the investor analysis is distinct from the borrower analysis. Investors should assess the specific offering documents, investment strategy, fees, risks, liquidity restrictions, conflict disclosures, portfolio construction, valuation practices, and reporting framework before making an investment decision.
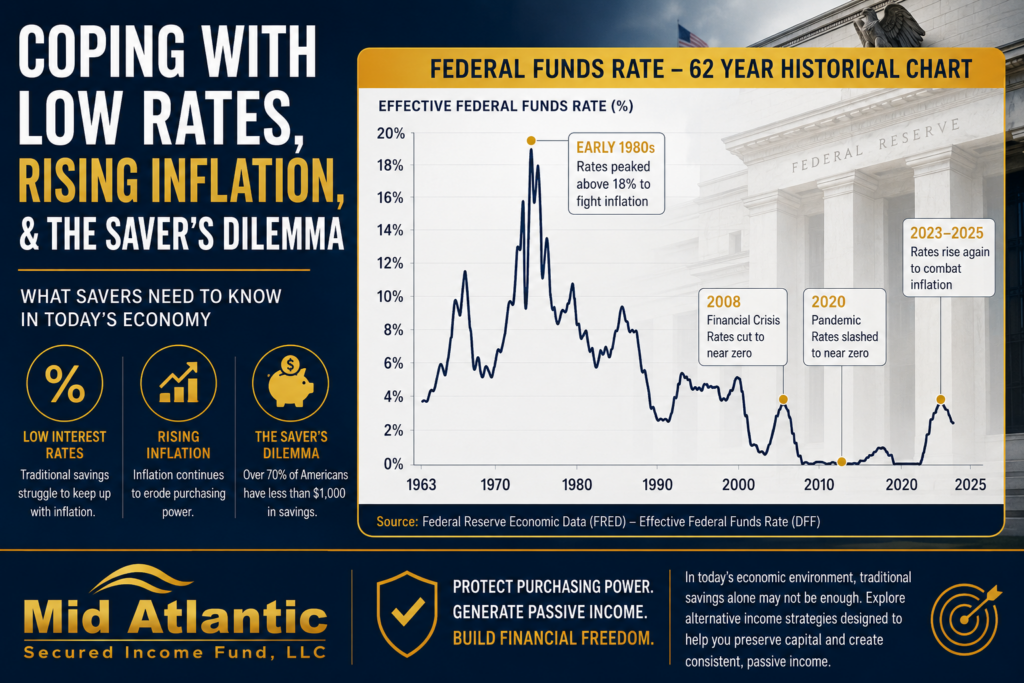
At Mid Atlantic Secured Income Fund, senior-secured, first-position real estate lending, disciplined underwriting, collateral quality, and transparent investor reporting are central considerations in the fund’s stated approach. However, a borrower financing product offered through an alternative lending platform should not be assumed to be held by, collateralize, or generate returns for the investment fund. The applicable offering documents and transaction materials control.
Private credit investments can involve loss of principal, illiquidity, borrower default, collateral-value changes, construction delays, and other risks. They are not a substitute for cash or individualized investment, tax, legal, or retirement-account advice. Accredited investors, including self-directed IRA investors, family offices, and RIAs, should review relevant documents with qualified advisers and consider whether a particular investment fits their objectives and constraints. Past performance does not guarantee future results.
Prepare for the Questions Before You Need Capital
The strongest development financing request is one that treats diligence as part of project planning rather than an obstacle after a contract is signed. Borrowers who can clearly explain the site, budget, construction team, collateral, and repayment plan give lenders a better basis for evaluation.
For investors, the same discipline applies from a different angle: understand what the strategy owns, how risks are managed, what information is reported, and where liquidity limitations apply. Careful preparation does not remove development risk, but it creates a more informed foundation for evaluating it.