Atlanta is not one real estate market. A stabilized multifamily asset near a major employment center, an infill redevelopment site, and a land parcel awaiting entitlement can respond very differently to the same interest-rate move or shift in buyer demand. That distinction should shape any Atlanta real estate market outlook, particularly for investors evaluating private real estate credit and borrowers planning business-purpose financing.
For capital allocators, the central question is not whether Atlanta will rise or fall in a single headline. It is whether a specific loan can be underwritten with sufficient collateral coverage, a clear repayment path, realistic assumptions, and appropriate protection against changing market conditions. For borrowers, the question is whether the project has a credible business plan, complete documentation, and enough time and contingency to execute.
Atlanta Real Estate Market Outlook Starts With Segmentation
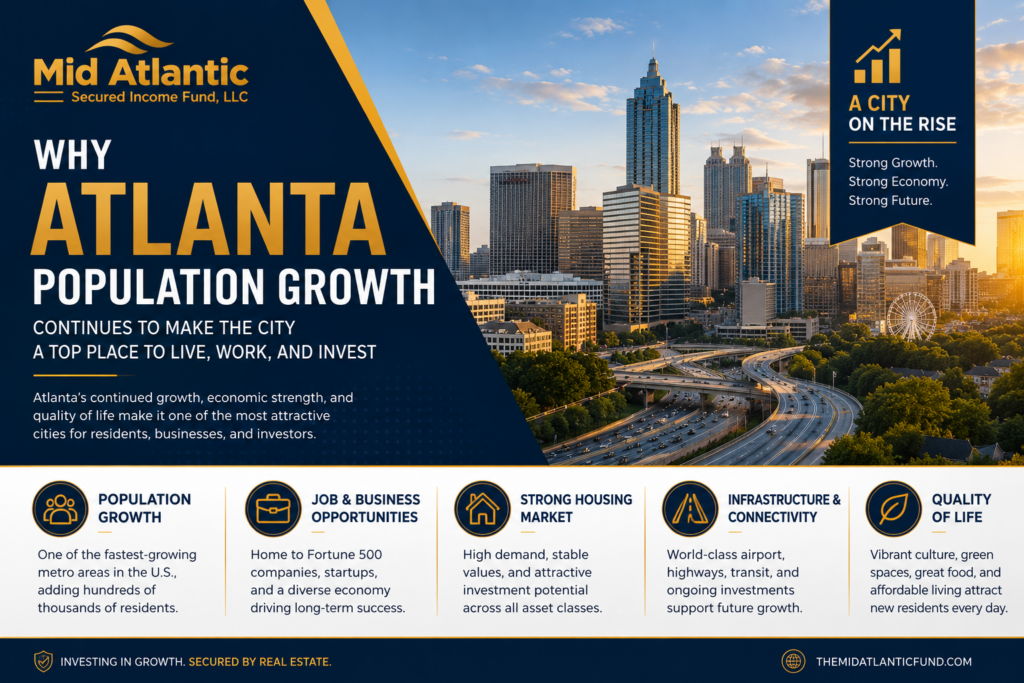
Metro Atlanta benefits from a broad economic base, population scale, transportation infrastructure, and a diverse set of commercial and residential submarkets. Those characteristics can support long-term demand, but they do not remove real estate risk. Supply, leasing activity, construction costs, insurance, property taxes, zoning, and financing availability can vary materially by property type and neighborhood.
A market outlook should therefore separate the asset from the broader metro narrative. Residential properties may be influenced by affordability, resale inventory, and household formation. Multifamily performance can depend on local deliveries, concessions, operating expenses, and tenant turnover. Industrial demand may reflect logistics patterns and tenant concentration. Office and retail require close attention to leasing quality, tenant financial strength, remaining lease term, and capital needs.
Land and development opportunities require another level of caution. Their value often depends on approvals, utilities, access, environmental conditions, construction budgets, and the availability of takeout financing or end-buyer demand. A positive view of Atlanta does not substitute for diligence on any of these property-specific factors.
The Credit View: Repayment Before Appreciation
Private real estate lending should be evaluated as a credit decision, not as a prediction about future property appreciation. A borrower may have a compelling renovation, construction, acquisition, or redevelopment plan. The lender still needs to understand how principal and interest are expected to be repaid if the project takes longer, costs more, or sells for less than anticipated.
That analysis begins with the collateral. Location, property condition, marketability, title, insurance, sponsorship, and third-party valuation each matter. So do the seniority of the lien, the scope of any existing debt, and the rights that govern a lender’s remedies if a borrower defaults. Senior-secured, first-position real estate lending can offer a defined position in the capital structure, but it does not eliminate losses, delays, legal expense, valuation uncertainty, or illiquidity.
A disciplined underwriting process also tests the borrower. Experience with comparable projects, liquidity outside the transaction, equity invested, contractor oversight, leasing capability, and prior execution history may all affect the probability of a successful outcome. Strong collateral and a capable sponsor are complementary protections. Neither should be treated as a substitute for the other.
Why exit assumptions deserve scrutiny
Every loan should have a clearly identified repayment source. That may be a property sale, refinance, operating cash flow, recapitalization, or another documented liquidity event. The preferred exit is not simply the one that works in an optimistic scenario. It is the one that remains plausible when marketing periods extend, financing becomes less available, or a valuation is revised.
In Atlanta, as in other large markets, liquidity can be uneven. A well-located and appropriately priced asset may attract buyers even during a slower transaction market. A specialized property, a site with unresolved entitlement issues, or a project requiring substantial additional capital may be harder to sell or refinance. Investors should consider those differences before relying on a broad metro-level outlook.
What Could Change the Outlook
The most useful market analysis identifies variables, not certainties. Financing costs and credit availability can affect purchase activity, refinancing capacity, and development feasibility. Construction labor and materials can pressure project budgets. Insurance and tax expense can reshape property-level cash flow. New supply can affect rents and concessions, while slower household or business demand can increase vacancy risk.
Regulatory and operational issues also matter. Zoning, permits, inspections, environmental matters, tenant disputes, title exceptions, and contractor performance can delay a business plan even where demand appears sound. For a lender, these are not secondary details. They may determine whether a borrower can complete the project and achieve the intended exit.
The appropriate response is not to avoid all uncertainty. It is to price, structure, document, and monitor risk with discipline. Conservative valuation analysis, clear covenants where appropriate, borrower reporting requirements, property inspections, and active servicing can provide useful controls. Their effectiveness depends on the specific transaction and the quality of execution.
How Accredited Investors Can Use This Outlook
Accredited investors considering private real estate credit should begin with the offering documents, not market headlines. A fund’s strategy, fees and expenses, liquidity provisions, conflict disclosures, concentration limits, loan sourcing process, valuation practices, servicing responsibilities, and risk factors deserve careful review. A private fund investment may be illiquid, may involve loss of principal, and may not be appropriate for every investor.
The relevant question is how a manager translates an Atlanta market view into loan selection. Investors may ask how collateral quality is assessed, how first-position security interests are documented, how repayment sources are evaluated, and how construction or redevelopment risk is monitored. They may also ask how the manager addresses geographic, borrower, property-type, and maturity concentrations.
Transparent reporting is especially valuable when markets are changing. Reporting should help investors understand portfolio activity, material developments, and the limits of available information. It should not be confused with a guarantee of performance or liquidity. Past performance, if presented in approved materials, does not guarantee future results.
Mid Atlantic Secured Income Fund emphasizes a capital-preservation-oriented approach centered on senior-secured, first-position real estate lending and disciplined underwriting. Eligible accredited investors should review current offering materials and consult their own legal, tax, and financial advisers before making an investment decision. A self-directed IRA investor should also evaluate custodial requirements, prohibited-transaction considerations, and other retirement-account issues with qualified advisers rather than relying on general market commentary.
What Atlanta Borrowers Should Prepare Before Seeking Financing
Qualified borrowers pursuing business-purpose real estate financing can improve the quality of a lending discussion by presenting a coherent, documented transaction. The objective is not to create a polished story. It is to show how the property, borrower, budget, timing, and repayment plan fit together under reasonable assumptions.
For an acquisition, renovation, construction, redevelopment, site-development, lot-acquisition, or fix-and-flip request, lenders commonly need to understand the purchase contract or ownership history, property details, borrower entity, project budget, sources and uses, construction scope, relevant permits or approvals, comparable sales or leases, and proposed exit. The precise documentation and eligibility requirements vary by transaction.
Borrowers should be candid about constraints. A delayed permit, cost overrun, tenant rollover, unresolved title matter, or reliance on a future refinance is easier to evaluate when it is surfaced early. Incomplete information can slow diligence or lead to an inaccurate assessment of risk. A clear plan, supported by credible documents and realistic contingencies, is more useful than an aggressive valuation projection.
The alternative lending platform may also consider certain non-real-estate business-purpose financing needs, such as receivables, purchase orders, inventory, litigation-related financing, or automotive business financing. Those products are separate from the fund’s investor offering. Their availability, underwriting standards, collateral, and terms vary, and they should not be assumed to be held by or to provide returns to the investment fund.
A Disciplined Way to Read the Market
The Atlanta real estate market outlook is best treated as a framework for questions, not a forecast to follow blindly. Is demand sufficient for this specific property? What could impair cash flow, completion, sale, or refinance? How much downside is embedded in the collateral analysis? What happens if the expected exit is delayed? And does the structure recognize the difference between a favorable market narrative and a durable credit case?
For investors and borrowers alike, the most constructive next step is to replace broad assumptions with transaction-level diligence. That discipline may not make uncertainty disappear, but it can make decisions more informed, more transparent, and better aligned with the risks being taken.